Orchard Boulevard land tender draws S$181.86m top bid, S$14m above runner-up
Intrepid Investments and TID Residential led five bids for the 99-year residential parcel. URA’s award decision is still pending.
Published 2026-10-30 · 5 min read
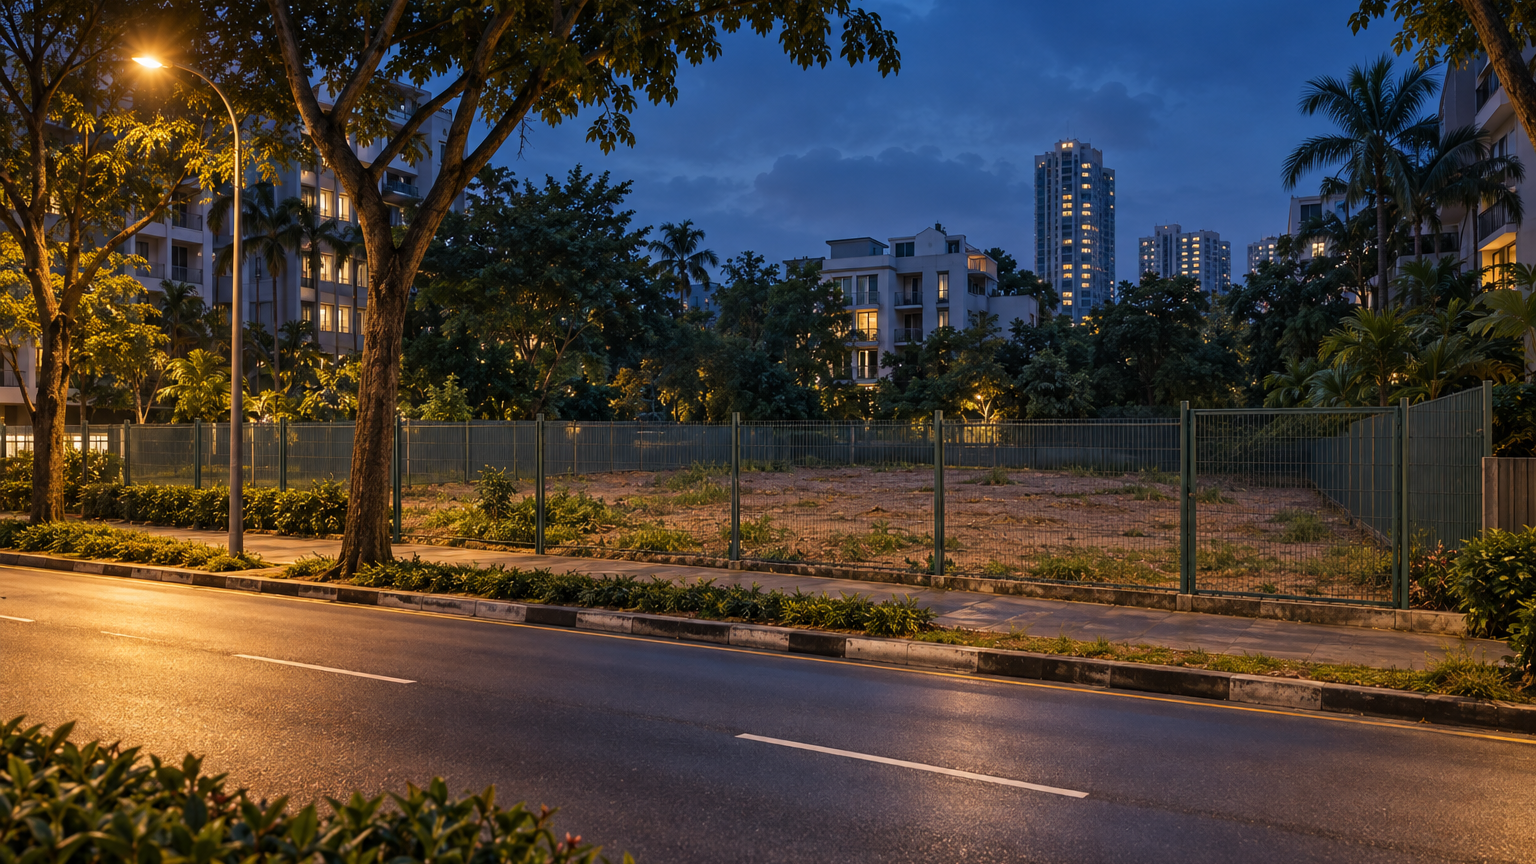
A joint bid of S$181.86 million led the five offers for the Orchard Boulevard residential land parcel when its government tender closed on 29 October 2026. Intrepid Investments Pte. Ltd. and TID Residential Pte. Ltd. offered S$14.01 million more than the next-highest bidder—a sizeable gap for this particular site.
For buyers watching for another Orchard-area condominium, this is an early step towards a possible new project, rather than a launch announcement. The Urban Redevelopment Authority (URA) has published the tender-closing result, but says the award decision will come only after evaluation.
How far ahead was the leading offer?
The joint bid was S$181,861,924, against S$167,850,000 from second-ranked GRC Development Pte. Ltd. Subtracting the two gives a difference of S$14,011,924; dividing that difference by GRC Development’s offer puts the leading bid 8.35% higher. These are calculations from the published tender figures, with the runner-up’s offer as the percentage denominator.
That comparison is more useful than the headline amount alone. Both bidders were pricing the same parcel in the same tender, so the difference shows how far apart their offers were without bringing in another location, lease or tender date. The five bids ranged from approximately S$139.90 million to S$181.86 million.
The full bidder names also matter. The first-ranked offer is recorded under Intrepid Investments Pte. Ltd. and TID Residential Pte. Ltd., rather than simply “Hong Leong”. Intrepid Investments is a wholly owned subsidiary of Hong Leong Holdings, while TID is a joint venture between Hong Leong Group and Japan’s Mitsui Fudosan. Those corporate connections explain the Hong Leong–TID shorthand attached to the bid.
For now, the precise description is highest bidder, not the developer that has secured the site. URA’s next decision will determine whether this offer becomes an awarded land transaction.
What does S$1,755 psf ppr actually buy?
The leading offer works out to S$18,890.82 per square metre of permitted gross floor area, or approximately S$1,755 per square foot per plot ratio, commonly shortened to psf ppr. In everyday terms, this measures the land bid against the amount of floor space permitted to be built—not against the land’s footprint alone.
The parcel has a site area of 3,438 square metres and a maximum permissible gross floor area of 9,627 square metres. Gross floor area is the planning measure of building floor space; it is a different denominator from the area of an individual apartment offered for sale.
That distinction is important when reading a tender headline beside condominium listings. S$1,755 psf ppr is a land-bid measure, not an apartment selling price. Multiplying it by a preferred apartment size would therefore not produce a meaningful purchase budget. The tender result supplies the land offer and development envelope, rather than a price list for homes.
The useful comparison here is between the competing land offers. A comparison with homes a buyer can actually purchase will need project-specific sale prices and unit information, which this tender-closing result does not provide.
What is known about the future residential site?
The confirmed starting point is a 99-year leasehold residential parcel at Orchard Boulevard. Its published land area and maximum floor area establish the scale of the development opportunity, but the tender result does not establish the finished condominium’s name, layouts, facilities or sales timetable.
For someone comparing new launches, the gap between those two sets of information is practical. A land parcel can enter a buyer’s watchlist because of its location, but choosing a home requires a much closer view: how rooms fit together, which direction a unit faces, and how the building sits within its surroundings. Those remain questions for later project information, rather than conclusions to draw from the bid.
The same applies to shared spaces. Without a verified design and unit mix, there is no sound basis here to describe the future pool, landscaping, privacy between stacks or balance of smaller and larger homes. None of those features is settled by the tender figures presented in the closing result.
So the buyer-relevant development is the emergence of a potential residential project to follow—not yet a set of units that can be ranked against an existing shortlist.
The next milestone is the award decision
URA closed the tender on 29 October 2026 and explicitly separated that announcement from an award. It said a decision would be publicised after the bid had been evaluated.
That makes the next update straightforward: whether the authority awards the Orchard Boulevard parcel, and to whom. Project-level comparisons can become more useful as verified plans and sales information emerge.
For now, the clearest fact is the choice made at tender: Intrepid Investments and TID Residential were prepared to offer S$14.01 million more than the runner-up for this residential parcel. Whether that leading offer becomes the foundation of a new condominium now rests with URA’s evaluation.